How to File a Moving Insurance Claim for Damaged Goods
Damaged goods during a move? Learn how to file a moving insurance claim for damaged goods and maximize your recovery. Call (833)-484-8675 for expert moving help.
By Tyler Scott
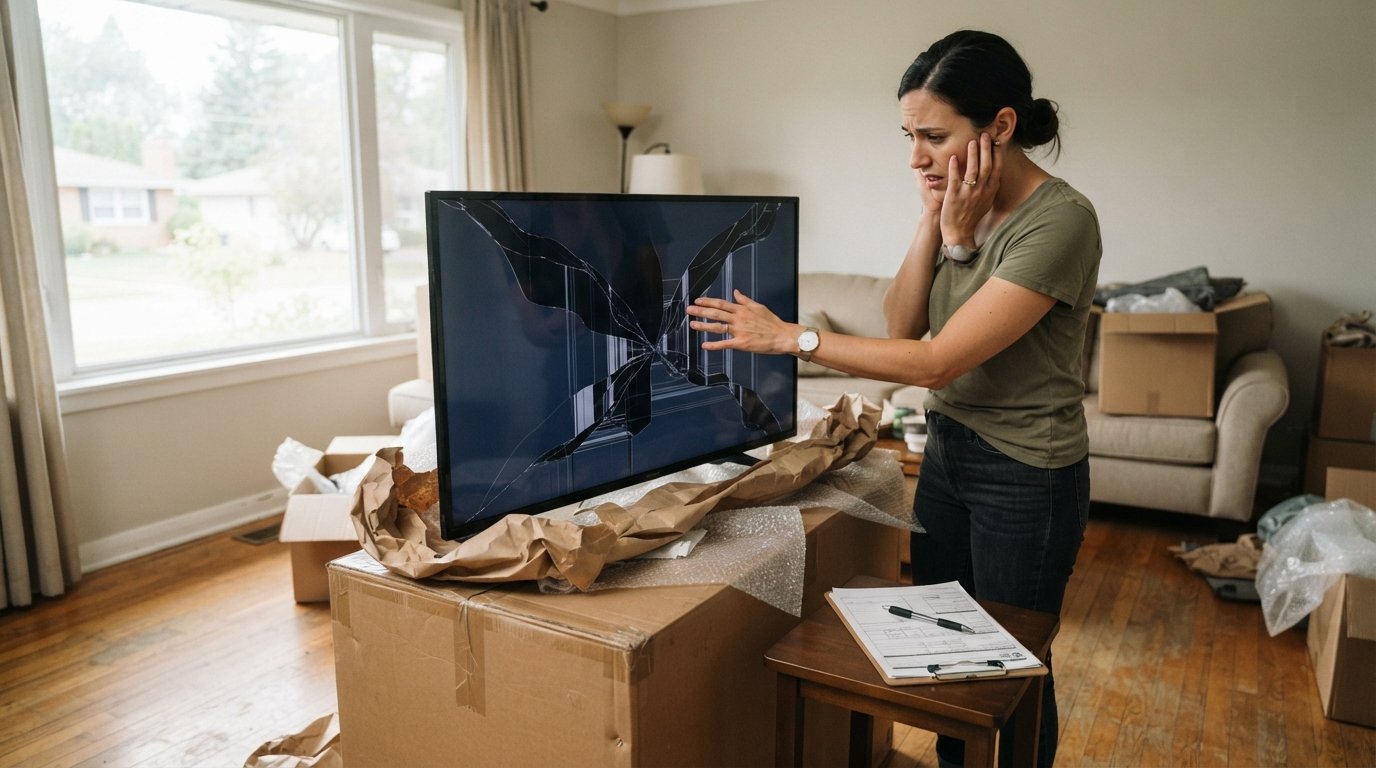
The moment you spot a cracked television screen or a shattered heirloom, the excitement of your new home can turn into frustration. You paid for professional movers expecting your belongings to arrive safely. When they do not, you have the right to seek compensation. However, the process is not as simple as making a phone call. It requires documentation, adherence to strict timelines, and a clear understanding of the coverage you actually purchased. This guide walks you through how to file a moving insurance claim for damaged goods so you can recover the maximum amount possible without unnecessary delays.
Understanding Your Coverage Before You File
Before you contact the mover, you must determine what type of liability coverage applies to your shipment. Many people assume they have "full coverage," but the moving industry uses specific terms that limit a carrier's liability. Standard moving insurance is not like your homeowner's policy. It is a valuation system that determines how much the mover must pay if an item is lost or damaged. Knowing this distinction is the first step toward a successful claim.
If you want a deeper dive into the different protection tiers, our guide on understanding moving insurance explains the nuances of carrier liability. For now, focus on the two main options: Released Value Protection and Full Value Protection. Released Value Protection is the basic, free coverage that comes with most moves. It reimburses you based on the weight of the item, not its actual value. For example, a 10-pound broken lamp might yield only 60 cents per pound, totaling $6.00. Full Value Protection costs extra but covers the replacement value of the item, often up to a deductible.
Check your Bill of Lading (BOL). This is the legal contract between you and the mover. It will state which valuation option you selected. If you opted for Full Value Protection, your claim should be straightforward. If you have Released Value, you must accept that the payout will be low, but you can still file. Never sign a BOL that leaves the valuation section blank. If you did, the mover might default to the lowest liability, which complicates your claim.
Step 1: Document Everything Immediately
The success of your claim hinges on the evidence you gather in the first 24 hours after delivery. Movers are trained to note exceptions on the inventory sheet, but you must be vigilant. As the truck is unloaded, have a copy of your inventory list in hand. Check off each box and item as it enters the house. Do not just sign the delivery receipt to get the movers to leave. Once you sign a clean receipt, you are acknowledging that everything arrived in good condition.
If you spot damage, note it on the mover's copy of the inventory sheet and your own. Take photos of the damaged item from multiple angles. Include close-ups of the specific damage (a scratch, a dent, a crack) and wide shots showing the item in the context of the room. If the packaging is damaged, photograph that too. It helps prove the damage occurred during transit. If an item is missing, note that on the sheet as well.
For high-value items, gather supporting documents. Dig up receipts, credit card statements, or appraisals. If you do not have a receipt, a screenshot of the current replacement cost from a retailer's website works. The more proof you have of the item's value and condition before the move, the stronger your case. Remember, the burden of proof is on you.
Step 2: Notify the Mover in Writing
Verbal complaints mean nothing in the claims process. You must submit a formal written claim. Most moving companies require you to submit a claim form within a specific timeframe, often 9 months from the date of delivery. However, do not wait. The sooner you file, the better. The moving company will provide a claim form, or you can find one on their website. If they do not provide one, write a formal letter.
Your written notification should include:
- Your full name, address, and the move date.
- The Bill of Lading number (BOL#) and the mover's job number.
- A detailed list of damaged or missing items.
- The estimated value of each item and the total amount you are claiming.
- Copies of photos, receipts, and the inventory sheet.
Send this letter via certified mail with a return receipt requested. This creates a paper trail. If you email it, request a read receipt. Keep a copy of everything you send. The mover will likely assign a claims adjuster to your case. The adjuster may contact you for more information or to schedule an inspection. Be cooperative but do not let them pressure you into a low settlement.
Step 3: Navigate the Settlement Offer
Once the adjuster reviews your claim, they will send you a settlement offer. If you have Full Value Protection, the offer should cover the repair or replacement cost, minus any deductible. If you have Released Value, the offer will be minimal. You have the right to accept or reject this offer. If the offer is fair, sign it and wait for the check. If it is low, you can dispute it.
To dispute a low settlement, you must provide evidence that the adjuster undervalued your item or misinterpreted the damage. For example, if they offer $50 for a lamp that costs $200 to replace, send them a link to the lamp at a store. If they claim the damage was pre-existing, send them a photo from before the move. Be persistent. Adjusters often have a range of authority, and a well-documented counteroffer can increase your payout.
Step 4: Escalate to a Regulator
If the moving company is unresponsive or refuses to pay a valid claim, you can escalate the matter. For interstate moves, the Federal Motor Carrier Safety Administration (FMCSA) regulates movers. You can file a complaint on their website. The FMCSA does not resolve claims, but they do track complaints and can penalize movers with poor records. For local moves, contact your state's Department of Transportation or Public Utilities Commission. Many states have a consumer affairs division specifically for moving disputes.
If the amount is significant, you might consider small claims court. This is often the fastest way to get a judgment against a mover. However, you must prove that the mover was negligent. If you have Full Value Protection, the contract usually requires arbitration instead of court. Check your BOL for an arbitration clause. Arbitration can be binding, meaning you cannot appeal the decision. Weigh the costs of arbitration against the potential payout.
When you are hiring a mover for a future move, you can avoid these headaches by choosing a reputable company. You can verify a mover's reputation through resources like Contractor.Homes, which connects homeowners with vetted professionals for various services, including moving and repairs. Ensuring you hire a licensed and insured mover is the best way to prevent damage and simplify the claims process.
Timelines and Deadlines You Must Respect
Missing a deadline can void your claim. The standard deadline to file a claim for interstate moves is 9 months from the date of delivery. However, some movers require you to note damage on the inventory sheet at delivery and file a formal claim within 30 days. Always check your BOL for the specific terms. If you miss the 9-month window, the mover can legally deny your claim.
Once you file, the mover has 30 days to acknowledge your claim in writing. They then have 120 days to pay, deny, or make a counteroffer. If they deny your claim, they must provide a reason. If you disagree, you have 60 days to appeal. This back-and-forth can take months, so patience is key. Keep a log of all communications, including dates and names of people you speak with.
Special Considerations for High-Value Items
High-value items like jewelry, art, and antiques often require separate insurance. Standard moving liability may cap coverage for these items at a low amount (e.g., $100 per item). If you are moving such items, you should purchase separate floater policies or third-party insurance. If you did not, your claim might be limited. Always inform the mover of high-value items before the move so they can note them on the inventory. If you failed to do so, you might be out of luck.
For items that are damaged beyond repair, the mover may take possession of the item and pay you the replacement cost. Do not throw away damaged items until the claim is settled. The adjuster may want to inspect them. If you discard them, you lose your leverage. Store them in a garage or storage unit until you receive a final settlement.
Preventing Damage Before It Happens
The best claim is the one you never have to file. When you pack, use high-quality materials. Double-box fragile items and use plenty of bubble wrap. Label boxes clearly with "Fragile" and the room they belong to. If you hire professional packers, they assume liability for the packing. If you pack yourself, you assume liability for any damage caused by poor packing. This is a crucial distinction. If a box you packed collapses and breaks a lamp, the mover is not responsible. If you want full protection, let the professionals handle the packing.
Take photos of your belongings before the move. This helps establish their condition. Also, consider hiring a mover that offers full-value protection. It costs more, but the peace of mind is worth it. When you get quotes, ask about their claims process. A reputable mover will be transparent about how they handle damage.
Filing a moving insurance claim for damaged goods is a test of your organizational skills and patience. By documenting the damage thoroughly, understanding your valuation coverage, and meeting every deadline, you can secure a fair settlement. Do not let a mover intimidate you into accepting less than you deserve. Stand your ground, provide evidence, and escalate if necessary. With the right approach, you can put the damage behind you and focus on enjoying your new home.