How to Budget for Cost of Living Changes After a Move
Budgeting for cost of living changes after a move starts with a side by side comparison of real expenses. Learn the steps that prevent surprise bills.
By Andrew Lewis
Your lease is signed, the boxes are stacked by the door, and the moving truck is booked. In the excitement of a fresh start, one critical task often gets pushed to the bottom of the list: rebuilding your budget for a new city where rent, groceries, utilities, and even a gallon of gas may cost far more or far less than what you pay today. A move is not just a logistics event; it is a financial reset. Households that skip this step often burn through savings in the first ninety days, just as deposits, commuting costs, and unfamiliar prices hit at once. The good news is that cost of living changes are predictable when you know where to look, and a little structured planning before the truck arrives can protect your emergency fund and your peace of mind.
Why Cost of Living Changes Hit Harder Than You Expect
Most people budget for the move itself: the truck, the boxes, the deposits, the pizza for friends who help carry furniture. Far fewer budget for the twelve months that follow, which is where the real financial pressure lives. National cost of living indexes, such as the ones published by the Council for Community and Economic Research, measure the price of housing, groceries, utilities, transportation, health care, and miscellaneous goods and services in hundreds of metro areas. The gap between the most expensive and least expensive metros in the United States regularly exceeds 100 percent, meaning the same salary can feel generous in one city and tight in another.
The tricky part is that cost of living changes rarely move in one direction. You might relocate to a city with cheaper rent but much higher car insurance, or a place with lower taxes but pricier electricity. These mixed signals make it easy to assume you are saving money when your actual monthly outflow is climbing. The only reliable way to know is to build a side by side comparison using your real spending, not national averages.
There is also a timing problem. A large share of your new expenses, such as first month rent, security deposits, utility connections, and renters insurance, land in the same four week window. Without a dedicated cash buffer, families end up financing the transition on credit cards and paying interest for months. Treating the post move period as its own budget, separate from the move itself, is the single most effective habit you can build.
Step One: Build a Side by Side Cost of Living Comparison
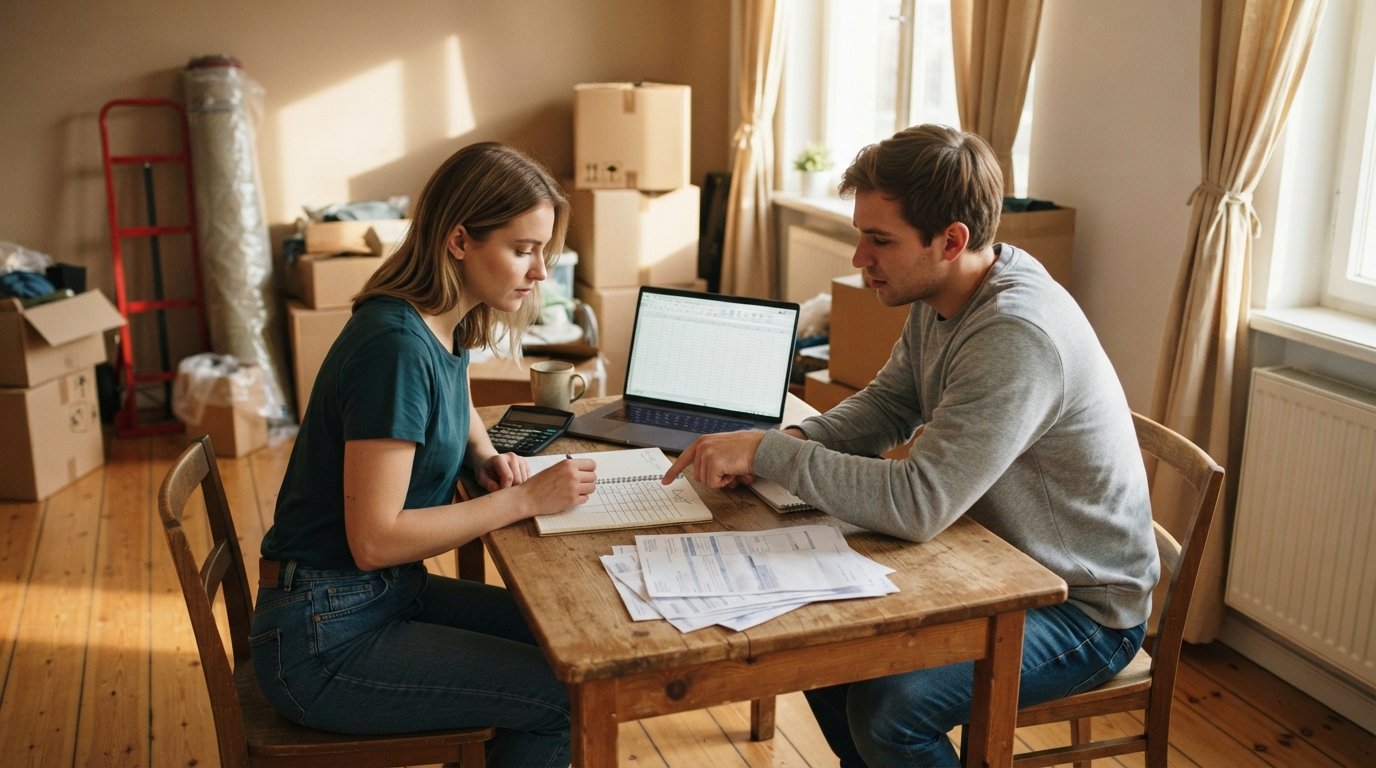
Start by listing your current monthly expenses in a spreadsheet or budgeting app, grouped into fixed costs and variable costs. Fixed costs include rent or mortgage, loan payments, insurance premiums, phone plans, and subscriptions. Variable costs include groceries, dining out, fuel, transit, utilities, and personal care. For each line, write down what you actually paid last month, not what you think you should have paid. Bank and credit card statements are your best source of truth.
Next, research the same categories in your destination city. Online cost of living calculators give you a fast starting point, but they are most reliable for housing and taxes, and less reliable for the way a specific household actually spends. To sharpen the picture, check local apartment listings for comparable square footage and neighborhoods, look up current utility rates from the local provider, and ask in community forums what a typical grocery run costs. If you are weighing whether to handle the heavy lifting yourself or bring in professionals, a cost benefit analysis of hiring movers can help you see where your money is best spent during the transition.
Once you have both columns, calculate the percentage difference for each category and for your total. A simple framework keeps the comparison readable:
- Housing: compare rent or mortgage plus property taxes and HOA fees
- Utilities: electricity, gas, water, internet, and trash, adjusted for climate
- Transportation: fuel, insurance, parking, tolls, and public transit passes
- Food: groceries plus a realistic dining out allowance
- Taxes and fees: state income tax, local sales tax, and vehicle registration
After you total the columns, look for the two or three categories driving most of the difference. Those are the ones worth negotiating, downsizing, or offsetting with a lifestyle change. If housing is 30 percent more expensive but transportation is 40 percent cheaper because you can walk or use transit, the net impact may be smaller than the raw rent number suggests. This kind of analysis turns a vague feeling of being stretched into a concrete plan.
Step Two: Estimate Your One Time Transition Costs
Cost of living changes are recurring, but the move itself comes with a wave of one time costs that can dwarf a monthly budget shift. Before you commit to a new lease or mortgage, list every expense you expect to pay in the first sixty days. Common items include the security deposit and first month rent, utility connection and deposit fees, renters or homeowners insurance for the new address, a moving truck or full service moving company, packing supplies, temporary storage, and travel costs such as fuel, flights, or hotels.
Many of these costs are easy to underestimate. Utility deposits alone can run several hundred dollars in markets where providers require them from new customers with no local payment history. If your new home needs minor repairs, painting, or appliance replacements, those bills arrive before you have had time to settle. For homeowners, the list expands to include closing costs, moving of major appliances, and any immediate fixes required by the lender or insurer. When projects go beyond your skills, it helps to know where to find vetted local contractors for home improvement and repair work so you can compare quotes instead of guessing at costs.
Add a 15 to 20 percent contingency on top of your one time estimate. Moves are famous for surprises: a truck that needs a second trip, a deposit that is higher than quoted, or a week of hotel stays when the closing date slips. A contingency line is not pessimism; it is the difference between a stressful month and a manageable one. Once you have the total, decide in advance which savings account will cover it and confirm the money is liquid and accessible.
Step Three: Rebuild Your Monthly Budget at the New Prices
With your comparison data and one time costs in hand, you can now build a fresh monthly budget for the new location. Do not simply carry over your old numbers. Rebuild each category from scratch using local prices, then compare the new total to your expected take home pay. If the new city has a state income tax or a different local tax structure, update your paycheck estimate as well, because a raise that looks generous on paper can shrink after taxes and higher housing costs.
A useful method is the 50 30 20 framework, adjusted for reality. Aim for roughly 50 percent of take home pay toward needs such as housing, utilities, groceries, insurance, and minimum debt payments; 30 percent toward wants such as dining out, hobbies, and travel; and 20 percent toward savings and extra debt payoff. In high cost cities, the needs bucket often exceeds 50 percent, which means the wants bucket has to shrink until income grows or housing costs come down. Being honest about this tradeoff early prevents the slow bleed of deficit spending.
Pay special attention to the categories most sensitive to location. Car insurance rates vary enormously by state and even by ZIP code, and a move across state lines requires a new policy, new registration, and often a new driver's license within a set number of days. Electricity and heating costs shift with climate, so a home in a hot, humid region may carry summer cooling bills that rival winter heating in a cold region. Grocery prices also vary by region and by store format, so plan a few weeks of actual receipts before locking in a grocery number.
Once the new budget is drafted, test it against your first two months of real spending. Track every category, even the small ones, and note where you were off by more than 10 percent. Those gaps are your adjustment targets for month three. Budgeting after a move is an iterative process, not a one time event, and the households that review their numbers monthly adjust fastest.
Step Four: Protect Your Cash Flow During the First Year
The first year in a new city is financially vulnerable because your income may lag your expenses. If you moved for a job, there may be a gap between your start date and your first paycheck, or a signing bonus that arrives later than expected. If you moved for family or lifestyle reasons, you may be searching for work while paying new city prices. Either way, cash flow management matters more than ever.
Build a bridge fund equal to at least three months of new city expenses, separate from your long term emergency savings. Use it only for the transition period and replenish it as soon as income stabilizes. If your employer offers relocation assistance, read the fine print on what is reimbursed, when, and whether it is taxable. Many relocation packages cover moving costs but not the higher rent or utility deposits, so do not assume the package solves the whole problem.
You can also smooth the transition by timing large purchases. Delay furniture upgrades, new electronics, and non essential subscriptions until you have lived in the new city for a full quarter and understand your real spending patterns. Negotiate where you can: ask about waived application fees, reduced deposits for good credit, or introductory rates on internet and utilities. Small wins in the first ninety days compound into meaningful savings over a year.
Step Five: Review and Adjust Every Quarter
Cost of living is not static. Rent renewals, insurance renewals, utility rate changes, and tax assessments all shift over time, and your own habits change as you learn the new city. Set a calendar reminder every three months to review your budget against actual spending. Ask three questions: which categories drifted upward, which drifted downward, and what one change would most improve next quarter's numbers. Then make that change before the next review.
If you are planning a move and want to reduce the financial uncertainty before you go, start by getting accurate numbers for the moving portion of your budget. You can request free moving quotes to compare guaranteed pricing from vetted professionals, which turns one of the largest variable costs into a known quantity. Knowing your moving cost precisely makes it far easier to budget for everything that follows: the deposits, the utility setup, the new rent, and the everyday cost of living in your new city.
Budgeting for cost of living changes after a move is ultimately an exercise in paying attention. The families who thrive after relocation are not the ones with the highest incomes; they are the ones who compared real numbers, built a buffer, and adjusted quickly when reality diverged from the plan. Start your comparison early, fund your transition costs, rebuild your monthly budget at local prices, and review it regularly. Do that, and your new city becomes a place where your money works for you instead of a place where you are constantly catching up. FreeQuotes.Contractors